This content is for informational purposes only and does not constitute legal advice or create an attorney-client relationship.
If your solar company went out of business, your loan doesn’t automatically go away. Learn how installer and lender obligations differ and what to do next.
Last updated: October 2026
What Happens to Your Solar Loan If the Installer Goes Out of Business?
You call the company that installed your solar panels, and the number is disconnected. The website is gone. Maybe your system stopped producing, your roof is leaking, or the project was never finished. Meanwhile, the loan payment still shows up every month.
This situation is more common than many homeowners realize. When a solar company goes out of business, your solar loan generally does not go away automatically. In most transactions, the installer and the lender are separate parties with separate obligations. The installer’s closure may affect your warranties, repairs, and potential claims, but it does not automatically cancel a separate financing agreement.
Want Help From The Law Firm Solely Focused on Solar Panel Lawsuits?
Click below and complete the form to learn more.

That’s exactly what happened to Angella. Her installer, Victory Solar, closed its doors and filed for bankruptcy while she was still dealing with a roof leak that kept coming back. The company was gone, but her solar loan wasn’t. Prevost Law Firm ultimately represented her in a claim against her solar lender. Every case is different, and prior results do not guarantee a similar outcome.
Below, we explain why that happens, what may still be available to you, and practical steps you can take. You can also check whether your installer is still operating in our Out of Business Installer Database.
Does My Solar Loan Go Away If the Solar Company Goes Out of Business?
No. An installer going out of business does not automatically eliminate your obligation to repay a solar loan. Your financing agreement is generally separate from the installer’s obligations. The installer shutting down, stopping operations, or filing bankruptcy does not by itself cancel your obligations under that agreement.
Think of it as two relationships. The installer obligations cover the sale, installation, workmanship, and often certain warranties. The financing obligations cover what you borrowed, the interest, and your payment schedule.
Whether you have claims or defenses that could affect the loan depends on your contract, how the transaction was structured, what was represented to you during the sale, and applicable law. That’s why the answer is rarely “the loan is gone” and more often “it depends on the facts.”
Who Owns and Services My Solar Loan Now?
The company you pay each month may not be the company that made your loan or the company that currently owns it. Solar transactions often involve several parties, and knowing who each one is matters if a dispute arises.
Common parties include:
- The installer: the company that sold and installed your system
- The original lender: the company that funded the loan
- The loan holder: the company that currently owns the loan, which may be different from the original lender
- The servicer: the company that collects payments and handles your account, which does not necessarily own the loan
Loans are sometimes sold, and servicing can transfer to a new company. Our guide to the difference between a loan holder and a loan servicer explains why this distinction can affect who may be responsible for what.
What Happens to My Solar Warranty If the Installer Closes?
Some warranties may be affected when an installer closes, but not every warranty depends on the installer. Solar systems often carry more than one type of warranty, and each works differently.
- Workmanship warranty: Usually offered by the installer and covers installation quality, such as roof penetrations and wiring. If the installer is gone, this warranty may be difficult or impossible to enforce directly against the company.
- Manufacturer warranties: Panel and inverter manufacturers often provide their own product warranties. These may remain available, although terms vary. Some may require service by a certified installer or proof of registration.
Read more about the difference between a workmanship warranty and a manufacturer warranty.
This distinction matters in real life. Tracy’s installer, Empire Solar, broke the tiles on her roof during installation and later went bankrupt. She still had warranties on the solar equipment, but no one was left to answer for the installation damage. Douglas found himself in a similar position: he was counting on his installer’s warranty, then discovered the company had been out of business for about two years and never told him.
Review your warranty documents and contact the equipment manufacturer directly to ask what may still be covered. Keep in mind that a new installer may charge to diagnose or repair a system it did not install. Roof problems are especially common. If your roof is leaking and the installer is gone, see our guide on what to do when solar panels caused your roof to leak. Our article on solar panel repair covers other signs that your system may need service.
What If My Solar Installer Filed for Bankruptcy?
A solar company’s bankruptcy filing may pause or change how certain claims against that company proceed, but it does not necessarily eliminate your loan obligation. When a company files bankruptcy, the automatic stay generally pauses many lawsuits and collection actions against that company. The automatic stay is a court-ordered pause that takes effect when a bankruptcy petition is filed.
A bankruptcy stay is like pressing a pause button on debt collectors. When someone files bankruptcy, the law tells most creditors, “Stop trying to collect money for now.”
The type of bankruptcy matters. Chapter 11 generally allows a company to reorganize or otherwise address its debts through a court-supervised process, and the company may continue operating during the case. In Chapter 7, a trustee generally administers and liquidates available assets of the business.
In either case, homeowners with claims against the installer may need to follow bankruptcy court procedures, including filing a proof of claim by an applicable deadline. The requirements depend on the type and status of the bankruptcy case.
Chantel experienced this firsthand. Her installer, Titan, started her installation but never finished it, then went bankrupt, leaving her family with an incomplete system and the bill for it.
For examples of how specific installer and lender bankruptcies have played out, see our installer-specific guides below. Because these cases change over time, check the latest status before relying on any update.
Can I Bring Claims Against the Lender Instead?
Depending on the facts, you may be able to raise certain claims or defenses related to the installer’s conduct against the holder of your loan. One reason is the FTC Holder Rule, a federal rule that requires certain consumer credit contracts to include a notice preserving the consumer’s claims and defenses against the seller.
Depending on how the transaction was structured and the contract language involved, the Holder Rule may allow certain claims or defenses related to the seller’s conduct to be asserted against a holder of the financing agreement. It does not mean the lender is automatically responsible for everything the installer did.
Monetary recovery against a holder based on the Holder Rule notice is generally limited to amounts the consumer paid under the contract. Other federal or state laws may provide additional rights or remedies depending on the circumstances.
Potential claims often involve alleged misrepresentations about system performance, promised savings, financing terms, or tax credits. The Consumer Financial Protection Bureau’s August 2024 Issue Spotlight on solar financing described consumer complaints about sales practices, including how federal tax credits were presented. Learn more in our guide: What Is the Holder Rule and How Does It Protect Consumers?
What this has looked like in practice: In several cases where the installer had closed or disappeared, Prevost Law Firm pursued claims against the homeowner’s solar lender rather than the defunct installer. That includes Angella, Tracy, Douglas, and Rajeev, whose installer, Victory Solar, stopped responding shortly after installation. As Tracy pointed out, the lender wasn’t the company that caused her problems. But when the installer is gone, the financing side of the transaction may be where a claim can still be pursued. Settlement terms in these cases are confidential, and every case depends on its own facts.
Should I Keep Paying My Solar Loan?
Whether to continue making payments is an individual decision, and it’s worth understanding the consequences before you decide. Stopping payments may result in negative credit reporting, collection activity, or other consequences under the loan agreement, potentially including acceleration of the balance. Acceleration means the lender demands the entire remaining balance at once.
Continuing payments may avoid some of those consequences while a dispute is pending. There is no guarantee that negative credit reporting can later be removed.
The financial strain can be significant either way. Many homeowners end up paying a solar loan on top of a utility bill the system was supposed to reduce. For Tracy, resolving her claim meant she no longer had to worry about “double bills” heading into the hot summer months.
Be cautious about refinancing, too. Before refinancing a disputed solar loan, consider having the proposed transaction reviewed by an attorney. Refinancing may affect existing claims or defenses and could result in the debt being secured differently, including against your home.
Does a Solar Loan Affect Selling or Refinancing My Home?
It can, particularly if a UCC filing is connected to your solar loan. A UCC-1 financing statement is a public filing that may provide notice of a claimed security interest in specified collateral. In solar transactions, the collateral may include the solar equipment, and some filings may be recorded as fixture filings in real property records.
A UCC filing is not necessarily the same as a mortgage lien on your house. However, it may come up during a sale or refinance, and a title company or buyer may ask that it be resolved. What the filing covers and what it takes to address it depend on your documents.
Our guide explains how to check whether you have a UCC filing on your home.
What If I Didn’t Know My Solar Company Closed?
Some homeowners don’t find out their installer closed until something breaks, sometimes years later. Solar companies are not always required to notify customers when they stop operating, and many don’t.
Douglas learned his installer had been out of business for about two years only after seeing an ad about solar company closures and looking his installer up. Nothing had gone wrong with his system yet, but the warranty he had counted on was suddenly in question. If you went solar several years ago, it’s worth checking whether your installer is still operating before you need a repair. The checklist below explains how.
What If My Solar Installation Was Never Finished?
An unfinished installation does not automatically cancel the financing tied to it. In some cases, homeowners have been billed for systems that were never completed, never passed inspection, or were never turned on.
This is one of the most common situations we hear about. Chantel’s installer went bankrupt before finishing her system. Jerry, David, and Wendy each dealt with solar projects that stalled or were never completed. If your project was left unfinished, document what was and wasn’t done, and keep any messages about the timeline or the reasons for delays.
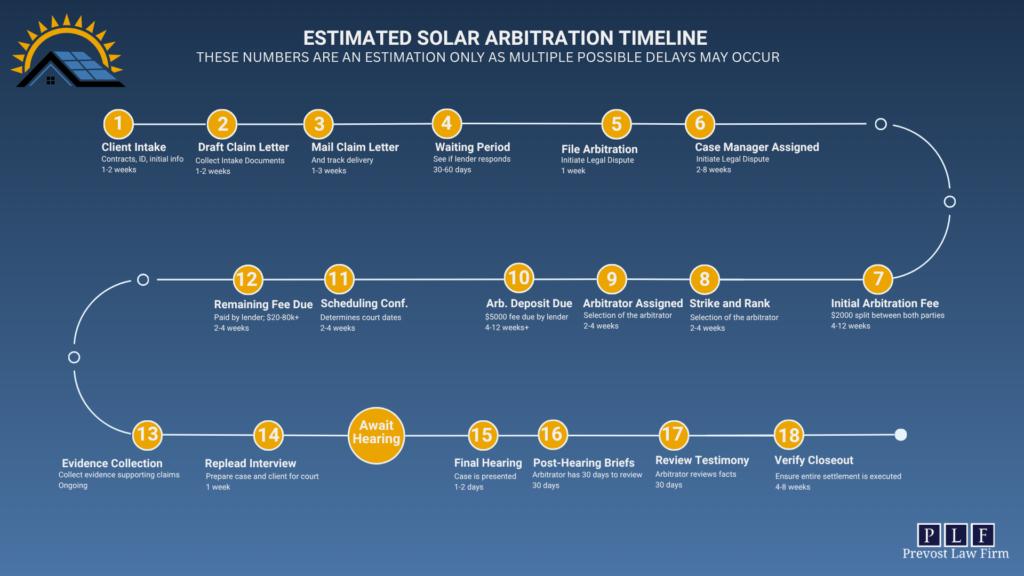
How Long Does a Claim Take When the Installer Is Gone?
Solar disputes often take more than a year to resolve, and the timeline depends on the facts and the parties involved. Among the homeowners who have shared their stories with us, Douglas’s case was resolved in about 19 months, while Angella’s and Rajeev’s each took about two years. All three said the wait was worth it.
The longer delay is often before a case starts. Tracy spent about three years dealing with her situation before she found legal help. Learn more about how long the process takes.
What Should I Do If My Solar Company Went Out of Business?
Start by confirming the company’s status and organizing your documents. These steps can help you understand where you stand:
- Check the installer’s status. Search our Out of Business Installer Database, and verify with your state’s business records or the company directly.
- Gather your paperwork. Collect your sales contract, loan agreement, proposal or savings estimate, warranty documents, and any texts or emails with the company.
- Identify your lender, loan holder, and servicer. Check your loan documents, recent statements, and any transfer notices to identify the companies involved and who currently collects your payments.
- Document the problem. Take dated photos of damage or unfinished work, and save your system’s production records if you have monitoring access. If your roof was damaged, follow our guide on how to document roof damage after a solar installation.
- Contact manufacturers. Ask whether panel or inverter warranties may still apply.
- Watch for bankruptcy deadlines. If the installer filed bankruptcy, deadlines for submitting claims may apply.
- Get your situation reviewed. A solar attorney can help you understand which claims or defenses, if any, may be available.
Be careful with companies that promise to cancel your loan for an upfront fee. Before you hire one, read the questions to ask before you hire a solar claim company.
Installer-Specific Guides
If you know which company installed your system, these guides cover what happened to specific installers and lenders and what it may mean for customers.
DISCLAIMER: Company statuses can change, so confirm the latest information before relying on any update.
Installers and lenders that filed bankruptcy:
Installers that shut down or disappeared:
FAQs: Solar Company Out of Business
Q: Can I still have a claim if my solar company closed years ago?
A: Possibly. Some homeowners don’t learn their installer closed until long after it happened. Whether a claim is still available depends on your contracts, the facts, and applicable deadlines, so it’s worth having your situation reviewed sooner rather than later.
Q: What if my solar installation was never finished before the company closed?
A: An unfinished installation does not automatically cancel a separate solar loan. Depending on the facts, you may have claims or defenses related to the incomplete work. Document what was and wasn’t completed, and keep all communications with the installer.
Q: If my solar company went out of business, do I still have to pay my loan?
A: An installer going out of business does not automatically cancel a separate solar loan. Whether you still owe the loan or have claims or defenses that could affect it depends on your financing agreement, how the transaction was structured, and the facts of your situation.
Q: Who do I call for repairs if my solar installer is gone?
A: Start with the equipment manufacturer to ask about product warranties, then consider a licensed solar service company. A new company may charge to inspect or repair a system it did not install.
Q: Can I sue the lender if the installer went out of business?
A: Possibly. Depending on the transaction and contract language, the FTC Holder Rule may allow certain claims related to the seller’s conduct to be asserted against the loan holder. Recovery may be limited, and every case depends on its facts.
Q: What happens to my solar loan if the installer files bankruptcy?
A: The installer’s bankruptcy may pause certain claims against that company, but it generally does not eliminate your loan with a separate lender. You may need to follow court procedures and deadlines to pursue claims against the installer.
Q: How do I find out if my solar company is out of business?
A: Check Prevost Law Firm’s Out of Business Installer Database, then verify with your state’s business-entity records and by contacting the company directly. Company status can change, so confirm before relying on any single source.
Get Help Understanding Your Options
When a solar company goes out of business, that closure does not automatically cancel a separate solar loan, but that doesn’t mean you’re out of options. Your warranties, the loan holder’s role, and the Holder Rule may all matter, depending on the facts.
Prevost Law Firm handles disputes involving solar installers, lenders, financing companies, and related parties. The homeowners featured in this article faced situations like these, and you can also read Rusty Stone’s story, another homeowner whose solar company vanished.
Every case is different, and prior results do not guarantee a similar outcome.
We’ll review your situation and help you understand the options that may fit your circumstances.
Want Help From the Law Firm Focused on Solar Panel Lawsuits?
This content is for informational purposes only and does not constitute legal advice or create an attorney-client relationship.