This content is for informational purposes only and does not constitute legal advice or create an attorney-client relationship.
Homeowners across the country are dealing with unfinished solar installations, misrepresentations by sales reps, warranty failures, and loan obligations they never expected.
Naturally, many people ask:
“Can we all join together and file a class action against Mosaic?”
It sounds appealing. Quick, collective, and powerful.
But for several important legal reasons, a class action against Mosaic is unlikely, even though many homeowners are experiencing similar issues. Read more about why class actions are unlikely in many solar cases.
Want Help From The Law Firm Solely Focused on Solar Panel Lawsuits?
Click below and complete the form to learn more.

Below is a clear breakdown of why class actions fail in this context, what has changed after recent industry bankruptcies, and what legal avenues remain available to homeowners.
1. Mosaic Contracts Specifically Prohibit Class Actions
This is the first, and most decisive, barrier:
Many Mosaic loan agreements include arbitration provisions and class-action waivers.
This means:
- A class-action waiver may prevent you from bringing a class claim against Mosaic.
- The terms of your agreement may also affect whether you can participate in a class action.
- Your agreement may require covered disputes to be brought individually through arbitration.
Courts often enforce valid arbitration provisions and class-action waivers, but the applicable agreement and legal circumstances must be reviewed in each case.
For homeowners whose agreements contain an enforceable class-action waiver, that provision can be a major barrier to participating in a class action.
2. Bankruptcy May Change Landscape and Remove Pools of Assets
Across the solar industry, multiple installers have filed for bankruptcy in the last 18 months.
When that happens, something important occurs:
The company’s largest secured creditor takes control of the remaining assets.
That means:
- There may not always be significant pools of recoverable assets sitting in a bankruptcy estate.
- There is often no financial reserve set aside that hundreds or thousands of homeowners could pursue collectively.
- A class action cannot target money that no longer exists within the company.
Put simply: after bankruptcy, the largest creditor typically steps in first. By the time homeowners seek relief, there is a possibility that no centralized fund exists for a class action to recover from, even if a class action were legally allowed.
This is a structural reality of how bankruptcy law works.
3. Every Homeowner’s Case Is Different, Which Prevents Class Certification
To qualify as a class, all plaintiffs must share:
- The same legal issues
- The same type of harm
- The same key facts
Solar cases vary significantly:
- Some systems were never installed.
- Some were partially installed.
- Some were installed improperly.
- Some include roof or electrical damage. (We have seen several victims of house fires.)
- Some involve misrepresentation about savings or tax credits.
- Some homeowners tried to cancel, and the installer never processed the request.
Those differences can make class certification difficult, depending on the claims and the proposed class.
4. Mosaic Is Usually Not the Party That Caused the Core Issue
In most cases we review, the primary issues relate to the installer, not the lender:
- Faulty workmanship
- No installation
- Abandoned projects
- Nonexistent warranty service
- Sales misrepresentations
- Failure to submit cancellation paperwork
A lender is not legally responsible for those actions unless the homeowner asserts individual rights under specific consumer-protection frameworks (such as the FTC Holder Rule). This must be done case by case.
This makes class actions legally inappropriate and practically unworkable.
5. What Does Work: Individual Claims Using the Holder Rule
Although a class action won’t move forward, homeowners still have powerful tools.
Under the FTC Holder Rule, a lender is subject to the same claims and defenses the homeowner has against the installer.
This is the mechanism that allows homeowners, in certain situations, to pursue:
- Loan relief
- Reimbursement of payments already made
- Damages tied to misrepresentation or incomplete work
But the Holder Rule must be applied individually based on the specifics of your installation, your documents, your timeline, and your damages.
6. Individual Cases Lead to Faster, Clearer Resolution
Instead of waiting years for a class action that legally cannot proceed, homeowners can take action now through:
- Individual arbitration
- Direct evidence-based claims
- Targeted negotiation using federal consumer-protection law
These cases move more quickly, allow for personalized review, and give homeowners far more control than a class action ever would.
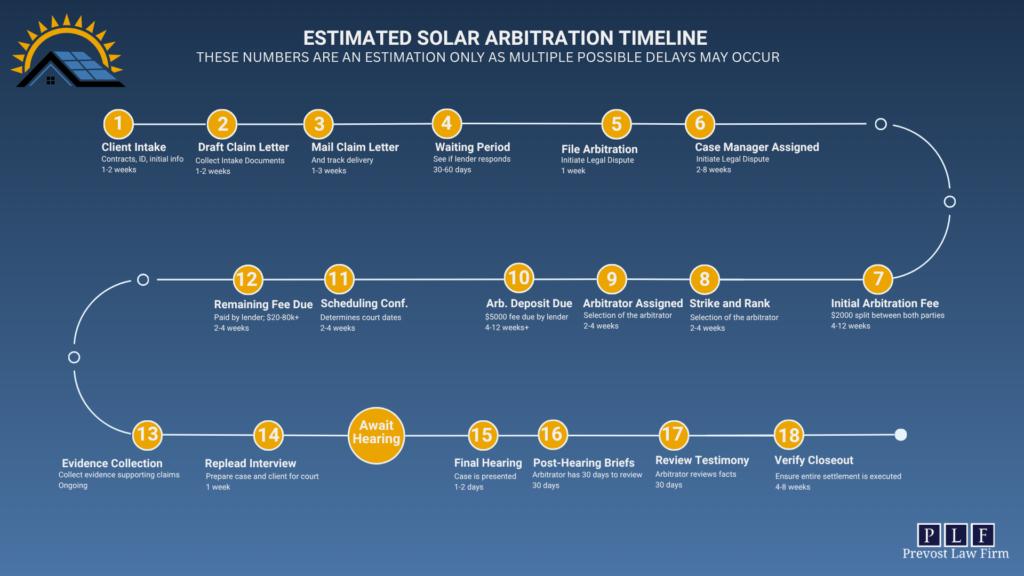
7. Arbitration Has Limits, But It Is Often the Most Consumer-Friendly Path Available
Arbitration is not perfect, but in the context of Mosaic loan disputes, it is often the most practical and effective option available to homeowners.
One key advantage is cost control. Consumer arbitrations typically cap filing fees and administrative costs, meaning homeowners are not exposed to the high court costs that often accompany traditional litigation. This lowers the financial barrier to bringing a claim.
Most consumer arbitrations also fall under streamlined rules, which are designed to reduce excessive paperwork, procedural delays, and discovery battles. As a result, arbitration cases generally move faster than state or federal court lawsuits, allowing homeowners to reach resolution in months rather than years.
Another important feature of arbitration is finality. Arbitration awards are extremely difficult to appeal. This means that if a homeowner prevails, the lender generally cannot drag the case through years of appeals in state or federal court, delaying relief and increasing costs.
That said, arbitration does come with limitations. It can restrict certain categories of damages, such as punitive damages or pain and suffering, depending on the governing rules and applicable law. Arbitration also limits formal discovery compared to court litigation.
Despite these drawbacks, arbitration often works in the homeowner’s favor by prioritizing efficiency, cost containment, and resolution. Particularly when combined with federal consumer-protection tools like the FTC Holder Rule.
In short, while arbitration is not a perfect system, it is often the most direct and effective way for homeowners to assert individual rights and obtain meaningful relief when a class action is not legally available.
How Prevost Reviews an Individual Mosaic Dispute
Prevost Law Firm reviews Mosaic-financed solar disputes involving unfinished or faulty installations, property damage, warranty problems, and alleged misrepresentations during the sale. We look at both the financing agreement and what the installer promised or delivered. Depending on the contract and the facts, the installer’s conduct may be relevant to a claim or defense involving the loan holder.
Our review also considers whether the agreement calls for individual arbitration and what relief may be available. Possible outcomes depend on the evidence and applicable law. They could include changes to the loan obligation or recovery of payments, but no result is guaranteed. Read more about potential solar claim outcomes here.
If you’re considering a claim, gather your Mosaic loan agreement, solar sales and installation contracts, payment history, proposals showing promised savings or tax benefits, messages with the installer or lender, and photos or records of any unfinished work or damage.
If You’re Dealing With Solar Problems, You Don’t Need a Class Action. You Need the Right Strategy
Given:
- Contractual class-action waivers
- Mandatory arbitration
- Post-bankruptcy asset transfers to secured creditors
- Highly individualized facts
- The installer-based nature of most solar failures
For many Mosaic loan holders, an individual claim may be a more practical path than waiting for a class action. Get a no-cost review of your potential claims here.
An individual claim may be worth evaluating. The available options and potential relief depend on the homeowner’s agreement, evidence, and circumstances.
If you want clarity on your specific situation, we offer a no-cost claim review.
We can walk through your contracts, installation history, and documentation to help you understand exactly what options apply to your case.
Request Your No-Cost Claim Review →
This content is for informational purposes only and does not constitute legal advice or create an attorney-client relationship.